The First Drug That Might Slow Huntington's Finally Has an FDA Date. The Market Sold the News.
uniQure's one-time gene therapy just got priority review and a May 1, 2027 decision date — the first in Huntington's history. The stock fell anyway. At $750 million of enterprise value net of cash, the gap between milestone and market is the trade.
On Monday, November 2, the FDA accepted uniQure's (NASDAQ: QURE) application for ifezuntirgene inilparvovec — the gene therapy the market still calls AMT-130 — and granted it priority review, with a target decision date of May 1, 2027. If the agency says yes, it will be the first treatment in history designed to slow Huntington's disease rather than merely manage its symptoms.
Two Wall Street desks called the acceptance an incremental positive within hours. The stock closed down 7.5% that day, kept sliding, and ended the week at $21.70 — down roughly 13% in five sessions, and 58% below its 52-week high of $51.72.
A binary event with generational stakes now has a date, and the market's response was to walk away from it. Understanding why — and what the numbers say about who's right — is the whole story.
The Disease That Comes With a Coin Flip
Huntington's disease is one of medicine's cruelest diagnoses. A single mutated gene — an expanded CAG repeat in the huntingtin gene, identified back in 1993 — produces a toxic protein that progressively kills neurons in the brain's striatum. Patients typically develop symptoms in their 30s or 40s: involuntary movements, cognitive decline, behavioral change. It is uniformly fatal, usually within 10 to 20 years of onset.
It is also autosomal dominant. Every child of a carrier has a 50% chance of inheriting it, and inheritance means the disease, not just risk of it. uniQure cites roughly 75,000 diagnosed patients across the U.S., EU, and UK, with hundreds of thousands more at risk. In the 33 years since the gene was found, the FDA has approved drugs that dampen the involuntary movements — and nothing, ever, that touches the disease itself.
That is the backdrop for what uniQure is attempting, and for why the Huntington's community has followed this program the way other patient groups once followed Casgevy or Zolgensma.
A Drug You Receive Exactly Once
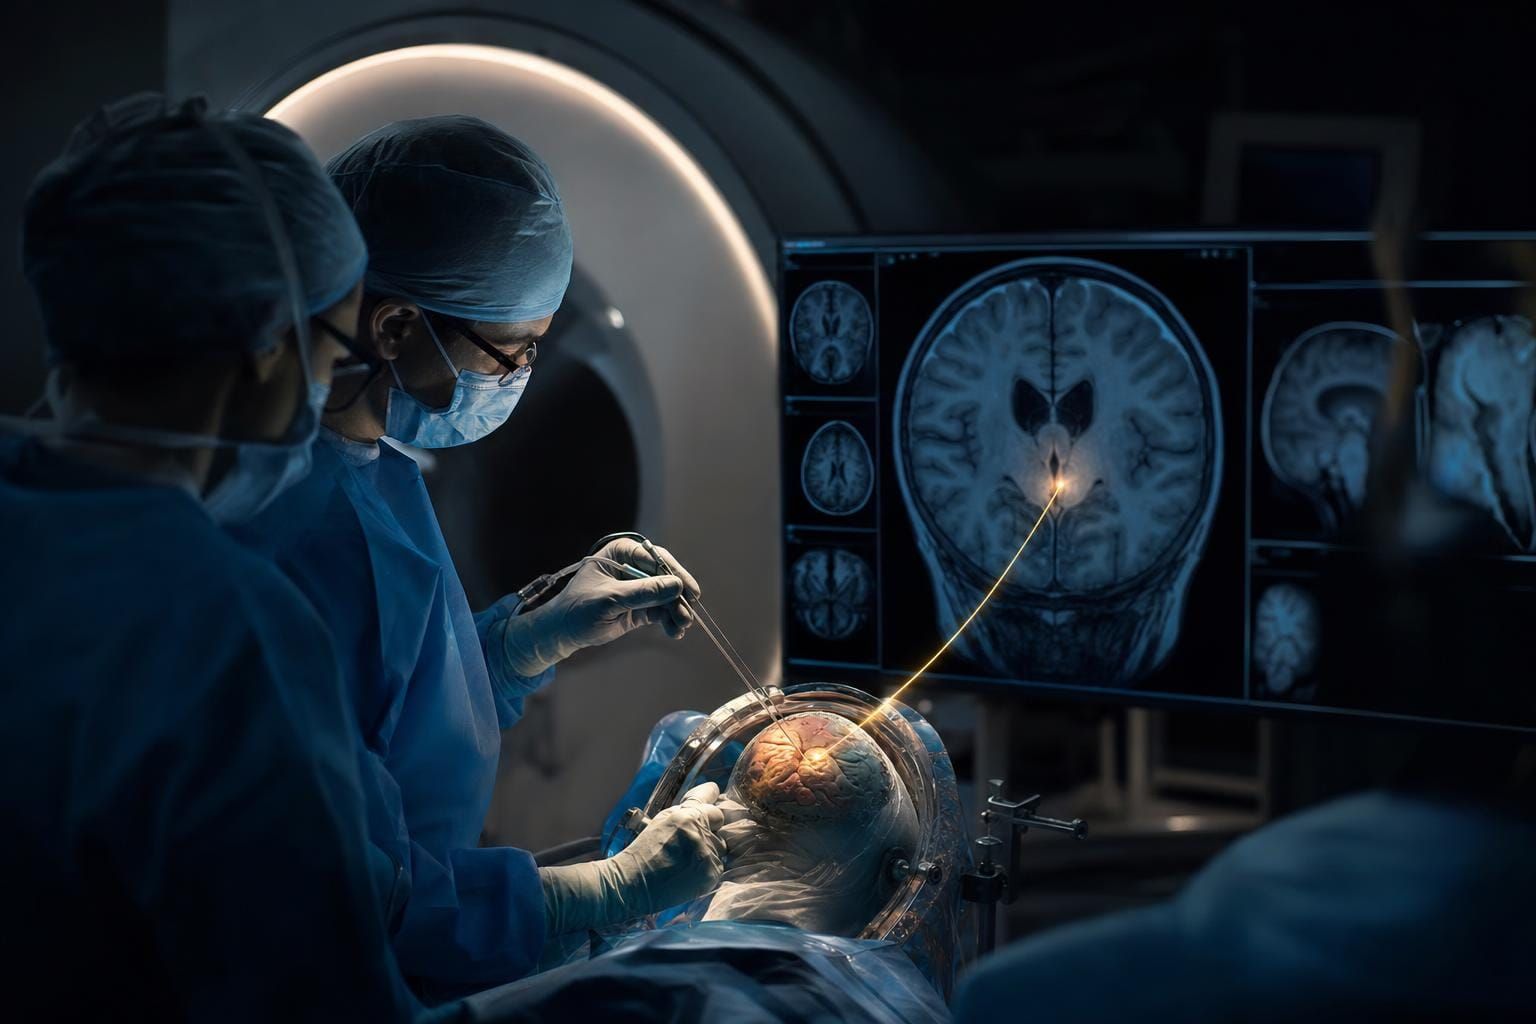
AMT-130 is not a pill. It is a one-time gene therapy: an engineered viral vector carrying a gene-silencing payload (a microRNA designed to suppress production of huntingtin protein, including its most toxic fragment), delivered directly into the striatum through MRI-guided neurosurgery. Hours in an operating room, catheters threaded deep into the brain, one administration — intended to last for life.
Across its Phase I/II program, uniQure has dosed 51 patients. The therapy holds Breakthrough Therapy, Fast Track, and Regenerative Medicine Advanced Therapy designations — the first Huntington's candidate ever to collect that full set.
Briefings like this are free to read with a free AlphaBriefing membership. Join free →
Eighteen Months of Whiplash
How a company gets from scientific triumph to a stock down 58% is a regulatory story worth recounting, because it explains exactly what May 1, 2027 does and doesn't settle.
September 24, 2025: uniQure reports 36-month data from its Phase I/II studies. Compared against a propensity-matched external control group built from the Enroll-HD natural history database, high-dose patients showed what the company reported as roughly 75% slowing of disease progression on a composite clinical measure. The Huntington's community, after decades of failed antisense and small-molecule programs, allows itself hope — and the stock more than triples in a single session, from $13.66 to $47.50.
November 2025: Five weeks later, the FDA reverses its prior guidance. The data, the agency now says, are not "adequate to provide the primary evidence in support of a BLA submission." It wants a sham-controlled Phase 3 — years of additional delay. Senior FDA officials make public comments widely read as skeptical of the program. The stock craters.
Spring 2026: Another reversal — this time in uniQure's favor. Following leadership changes at the agency, the FDA re-opens the door to a filing under the accelerated approval pathway. uniQure submits its BLA on September 2.
Late September 2026: Four-year follow-up data land "weaker than expected," in Stifel's words. The treatment effect, measured against those same external controls, looks softer at 48 months than it did at 36. QURE drops as much as 38% in a session.
November 2, 2026: The FDA accepts the filing, grants priority review, sets May 1 — and says it is "tentatively planning" to convene an advisory committee.
So the question the free section leaves you with is the one the market is wrestling with: the FDA just handed uniQure the fastest possible path to a historic approval, and the stock got cheaper. One of those two things is mispriced. Which one?
A free membership gets you access to every free article at AlphaBriefing.com — takes 30 seconds: Join AlphaBriefing
The rest of this briefing is for paid members: the three specific reasons the stock sold a positive catalyst, the enterprise-value math (what the market is actually paying for AMT-130 after you strip out $768 million in cash), the revenue scenarios for a $2 million-plus one-time brain surgery and the bottleneck nobody models, the advisory-committee risk framework, and the second ticker whose fate is chained to May 1.
AlphaBriefing Paid gets you every investment thesis, scenario framework, and catalyst brief we publish — the analysis private intel clients pay four figures for, at a fraction of that.