Nobody Voted to End the AI Trade. Wall Street Sold It Anyway.
A $2.9 trillion single-session wipeout, the Nasdaq in correction, and semiconductors' worst day since 2020. Inside the three forces that broke the AI trade on Thursday — and what today's jobs report means for the bounce.
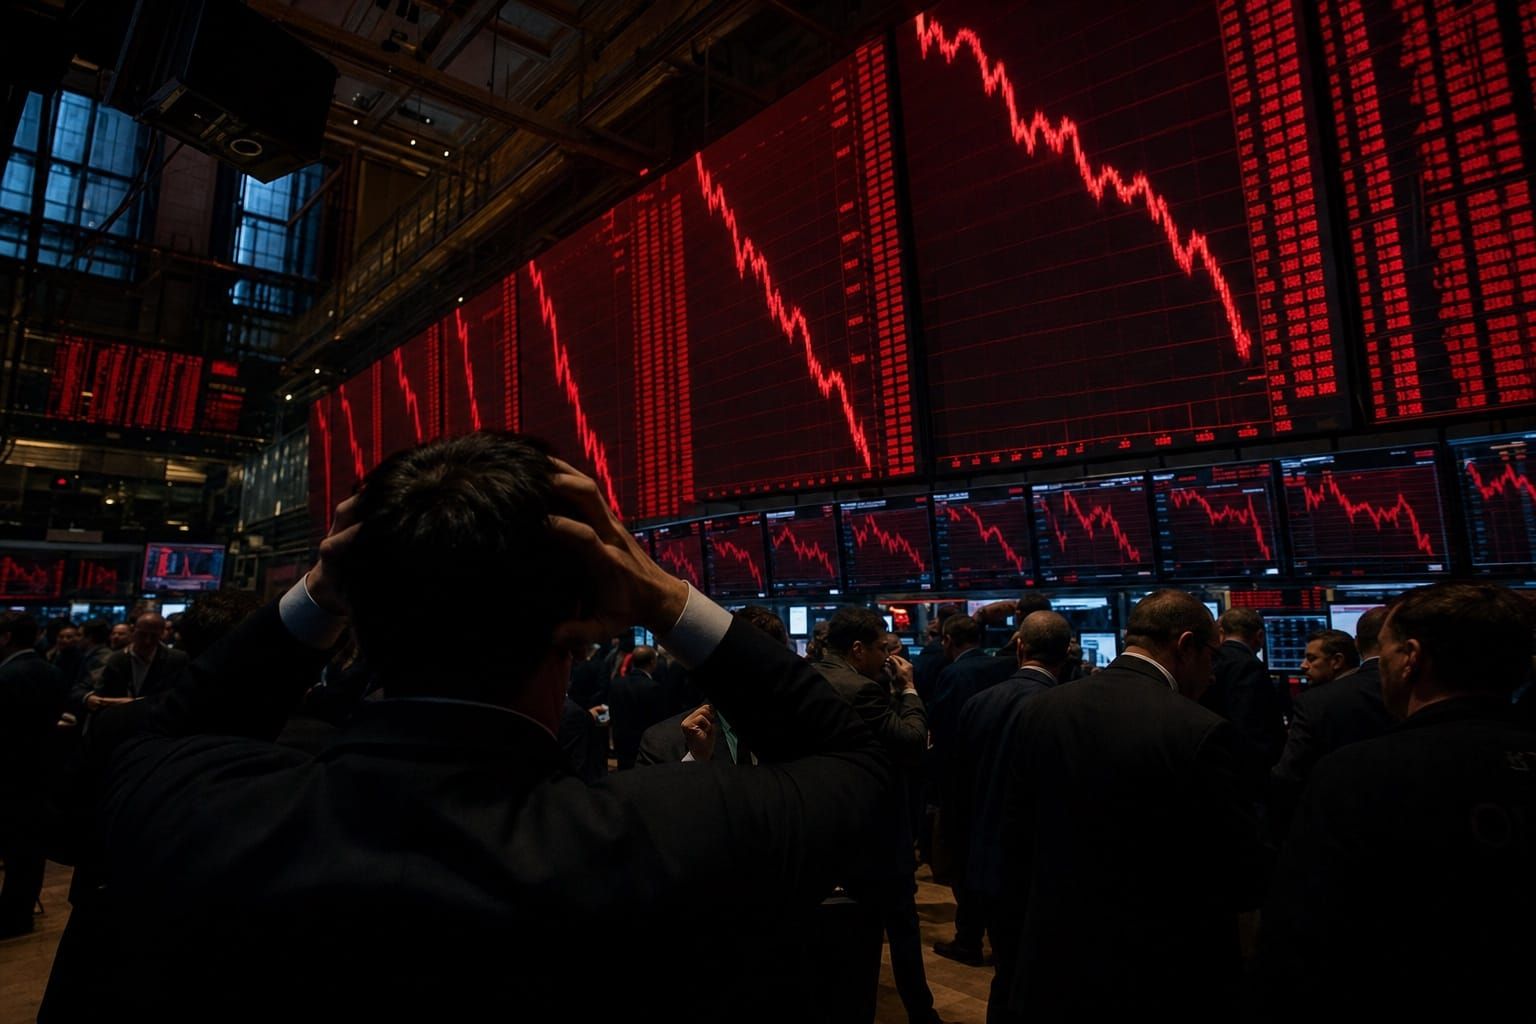
Wall Street got one trading day to enjoy the midterm results. On Wednesday, the Dow Jones Industrial Average jumped more than 1,500 points in a postelection relief rally. On Thursday, the market took it all back — and then kept going.
By the close on Thursday, November 5, the S&P 500 had fallen 4.4%, its worst single session since the "liberation day" tariff panic of April 2025, erasing an estimated $2.9 trillion in market capitalization — which MarketWatch called the largest one-day loss of market value on record. The Nasdaq Composite dropped 5.5% and closed in correction territory, more than 11% below the record it set in October. The Dow fell roughly 1,833 points, about 3.4%. And at the center of the storm, the Philadelphia Semiconductor Index collapsed 12.2% — with CNBC noting the iShares Semiconductor ETF logged its biggest one-day decline since the COVID crash of March 2020.
The single-name damage was brutal. Advanced Micro Devices fell 17.3%. Nvidia lost 9.3%. Palantir dropped 9.7%. Super Micro, fresh off a weak-margin quarter, slid another 8.5%. The AI-adjacent "neocloud" names fared worse: CoreWeave fell 9.8% and IREN lost 16.9% — before announcing after the close that roughly $4 billion in annualized revenue is being delayed into next year "due to customer request." The VIX, Wall Street's fear gauge, spiked from 16.6 to 28.2 in a single day. Even bitcoin, trading near $76,000, offered no shelter.
A selloff this fast is never about one thing. This one was about three.
1. Washington just changed the math on the buildout
The proximate trigger was political. Tuesday's Democratic sweep of the midterms handed the party control of Congress and a string of governorships — including Texas, the physical heart of the American data-center buildout. And as CNBC reported Thursday, investors concluded that Democrats are meaningfully more skeptical of unrestricted data-center construction than the Republicans they replaced: more friction on permits, more deference to communities pushing back on land, water, and electricity demands.
Texas governor-elect Gina Hinojosa told MarketWatch she is not ideologically opposed to data centers — but that community approval must come first. For a trade that has been priced on the assumption that hyperscalers can build as fast as they can pour concrete, that is a new variable.
"Right now, investors are questioning that $1.2 trillion of capex that we forecast for next year," Peter Boockvar, chief investment officer at One Point BFG Wealth Partners, told CNBC. "Well, maybe that's not going to happen." Eric Johnston, head of equities at Cantor Fitzgerald, went further: "The entire economy and the consumer and earnings growth are all levered to that buildout."
That last point is the one that spread the selling beyond tech. If AI capital expenditure is the main engine of American earnings growth — and increasingly of GDP growth itself — then anything that slows the buildout isn't a sector story. It's a market story.
Briefings like this are free to read with a free AlphaBriefing membership. Join free →
2. The risk-free rate finally bit
The second force has been building for months: interest rates. The 10-year Treasury yield sits near 4.8%, and the Federal Reserve under Kevin Warsh has shifted into a tightening posture — a recent CNBC survey of forecasters expected further rate hikes ahead, just not at the most recent meeting. Third-quarter GDP came in at a better-than-expected 3.4% annualized pace with September inflation accelerating, the Bank of England hiked rates on Thursday for the first time since the Iran war began, and euro-zone inflation has climbed to 4%.
"A compelling risk-free rate is causing investors to reconsider taking the risk in these volatile AI stocks" is how CNBC summarized Josh Brown's argument, with Brown pointing at that 4.8% yield: "You don't need to be at 80% U.S. stocks and have 60% of that exposure be tech."
This is the quiet regime change underneath the loud one. For most of the AI rally, equities were the only game in town. At nearly 5% guaranteed, they aren't. When a political shock hits a market that already has a cheaper alternative on offer, the exits get crowded fast.
3. The financing cracks were already visible
The third force is the one regular AlphaBriefing readers have watched develop for weeks: the AI trade's debt plumbing was creaking before a single vote was counted. CoreWeave's bonds were already yielding around 15%. Super Micro's latest quarter showed $19.9 billion in revenue with margins thin enough to spook the market. And on Friday morning, CNBC reported that Dutch bank ING is reportedly seeking bids for roughly $500 million across 12 data-center loans — including debt tied to a New Mexico Stargate site — a sign that some lenders may want to lighten their AI exposure rather than add to it.
IREN's after-hours disclosure that $4 billion in annualized revenue is slipping into next year at a customer's request lands in the same bucket. None of these items is fatal on its own. Together, they describe a buildout whose financing is getting more expensive and more selective at exactly the moment its political runway got shorter.
Correction or conclusion?
So is the AI trade over? Thursday's sellers behaved as if the answer might be yes. The counterargument showed up on the same tape.
"Nobody voted to make compute less scarce," Rob Sechan, founder of Newedge Capital Group, told CNBC — pointing to Microsoft's Azure business, which grew 48% year over year in its most recent quarter, as evidence the problem is capacity, not demand. His logic cuts the other way from the panic: "When new capacity gets harder to build, existing capacity becomes more valuable."
The valuation picture complicates the bear case too. MarketWatch's Philip van Doorn notes that after the rout, semiconductor stocks trade at their cheapest forward valuations in nearly seven years — the lowest since January 2019 — because earnings expectations have kept climbing while prices fell. Raymond James CIO Larry Adam called Thursday's "indiscriminate selling" a buying opportunity for investors with a longer horizon. Victoria Greene of G Squared Private Wealth flagged support near the S&P 500's 200-day moving average and noted that the day after a rout of this size has historically averaged a bounce of roughly 180 basis points.
None of that guarantees a floor. It does frame the real question: Thursday repriced the speed of the AI buildout. It did not produce evidence that demand for compute fell. Those are different problems, and the market charged one price for both.
What to watch now
The next catalyst arrives almost immediately: the October jobs report, due at 8:30 a.m. ET this morning. ADP's Wednesday print showed private employers adding 86,000 jobs, slightly above expectations, and jobless claims are hovering near their lowest levels since the 1960s. A hot number feeds the Fed-hike narrative that helped break the tape on Thursday; a soft one gives the market its excuse to bounce. Early Friday, U.S. equity futures were attempting to stabilize just above Thursday's settlement.
Beyond that, watch three dials: whether Democratic data-center skepticism hardens into actual legislation or stays at the statehouse level; whether more banks follow ING in quietly shopping data-center debt; and whether the 10-year yield holds below 5%. The AI trade survived expensive chips. It has never had to survive expensive money and hostile permitting at the same time.
If this analysis was useful, this is what AlphaBriefing does every day — markets and politics, connected to what it means for your money. A free membership gets you access to every free article on AlphaBriefing.com; paid members get the investment frameworks, scenario pricing, and catalyst calendars behind the paywall. Sign up free → — upgrade whenever it earns it.
Get this level of intelligence every day. Subscribe to AlphaBriefing — free, member, and paid tiers available.
Sources & Further Reading
- MarketWatch — Tech stocks log worst day since 2020 as carnage comes to the AI trade
- CNBC — CNBC's experts on whether the AI trade is ending and what investors should do next
- CNBC — AI debt concerns grow as ING reportedly seeks buyers for $500 million of data center loans
- CNBC — Neocloud IREN says $4 billion in annualized revenue being delayed due to customer request
- CNBC — The October jobs report is out Friday. Here's everything to expect
- MarketWatch — Chip stocks are the cheapest they've been in nearly seven years. How low is too low?
- CNBC — Private companies added 86,000 jobs in October, slightly higher than expected, ADP says
Disclaimer
AlphaBriefing is an independent intelligence publication. The content in this article is produced for informational and educational purposes only. Nothing published by AlphaBriefing constitutes financial, investment, legal, tax, or regulatory advice, nor should it be construed as a solicitation or recommendation to buy, sell, or hold any security, asset, or financial instrument.
All views expressed are those of the author at the time of writing and are subject to change without notice. Markets are volatile and unpredictable; past performance is not indicative of future results. Any investment involves risk, including the possible loss of principal.
AlphaBriefing and its principals, employees, or contributors may hold positions in securities or assets mentioned in this article. This should be considered a potential conflict of interest. No material relationship with any company referenced exists unless explicitly disclosed. Readers should conduct their own due diligence and consult qualified financial, legal, and tax advisors before making any investment decisions.
Information in this article is drawn from public sources believed to be reliable at the time of publication. AlphaBriefing makes no warranty, express or implied, as to the accuracy, completeness, or timeliness of any information herein. AlphaBriefing accepts no liability for any loss or damage arising from reliance on this content.
© AlphaBriefing. All rights reserved. Unauthorised reproduction or distribution is prohibited.